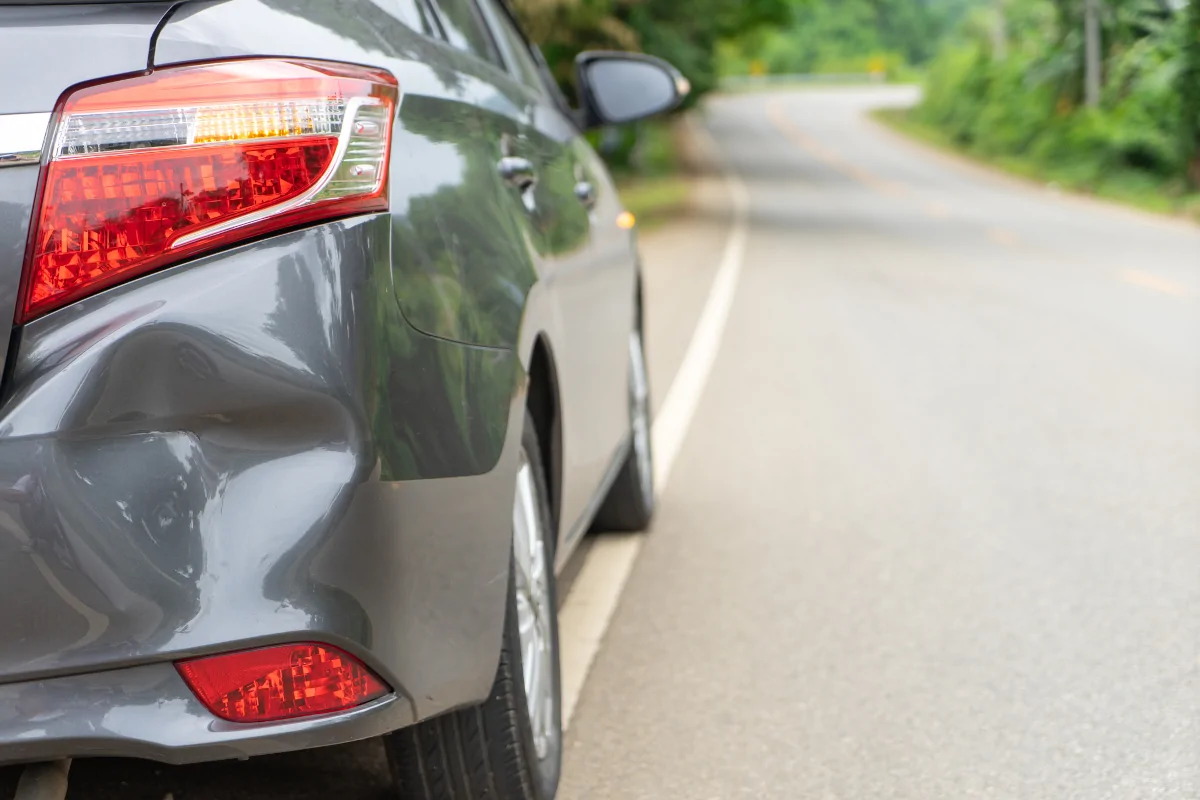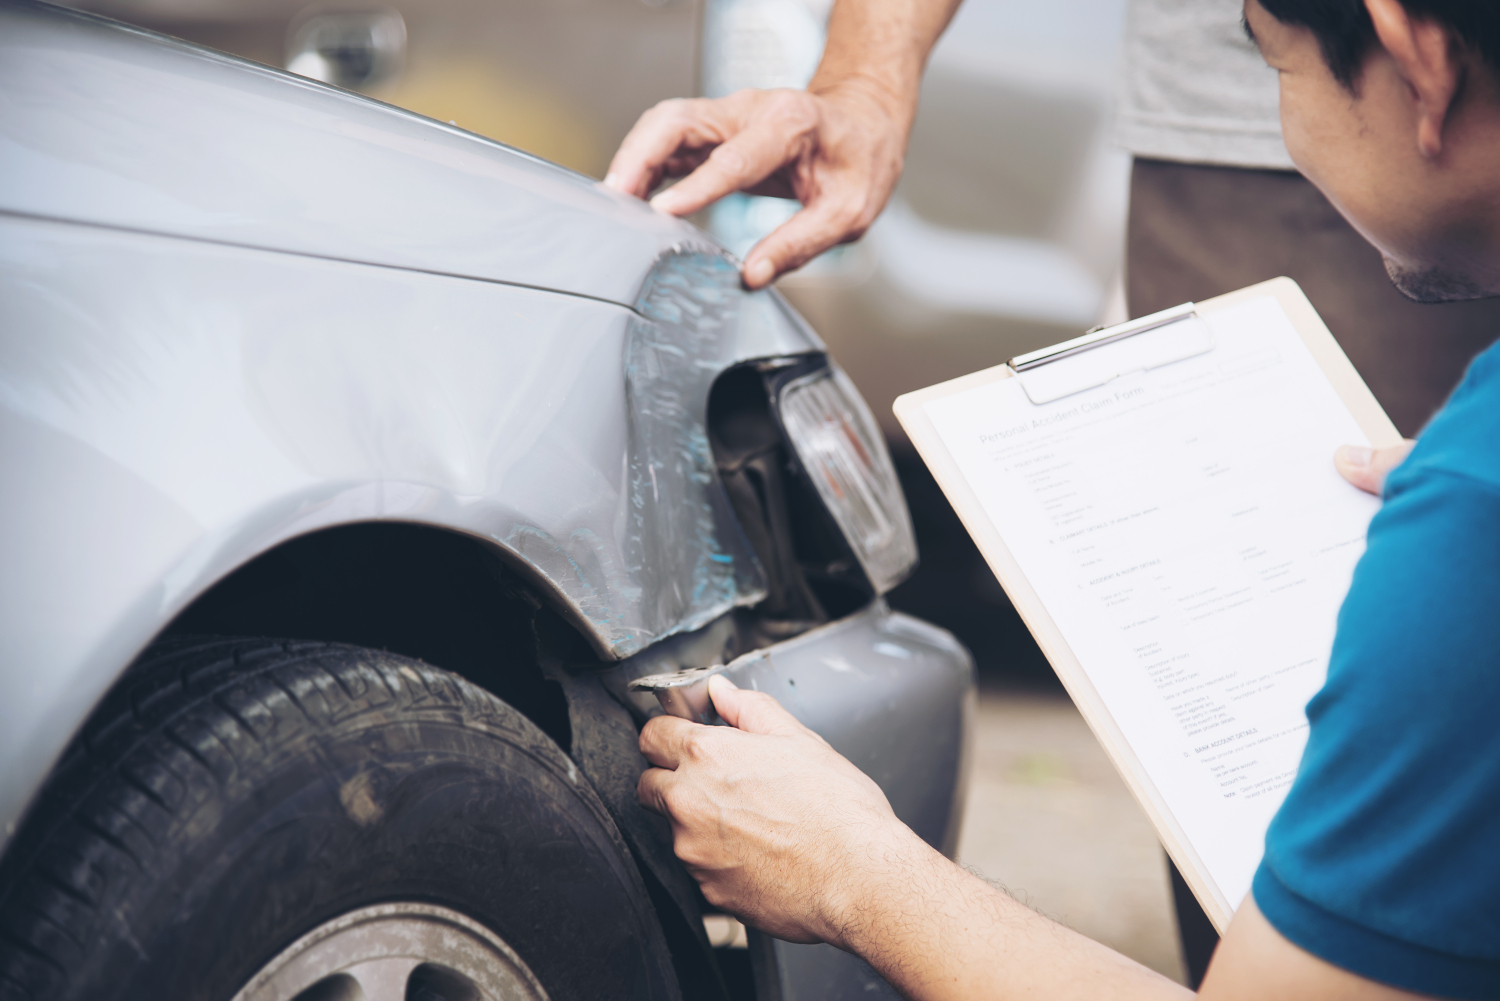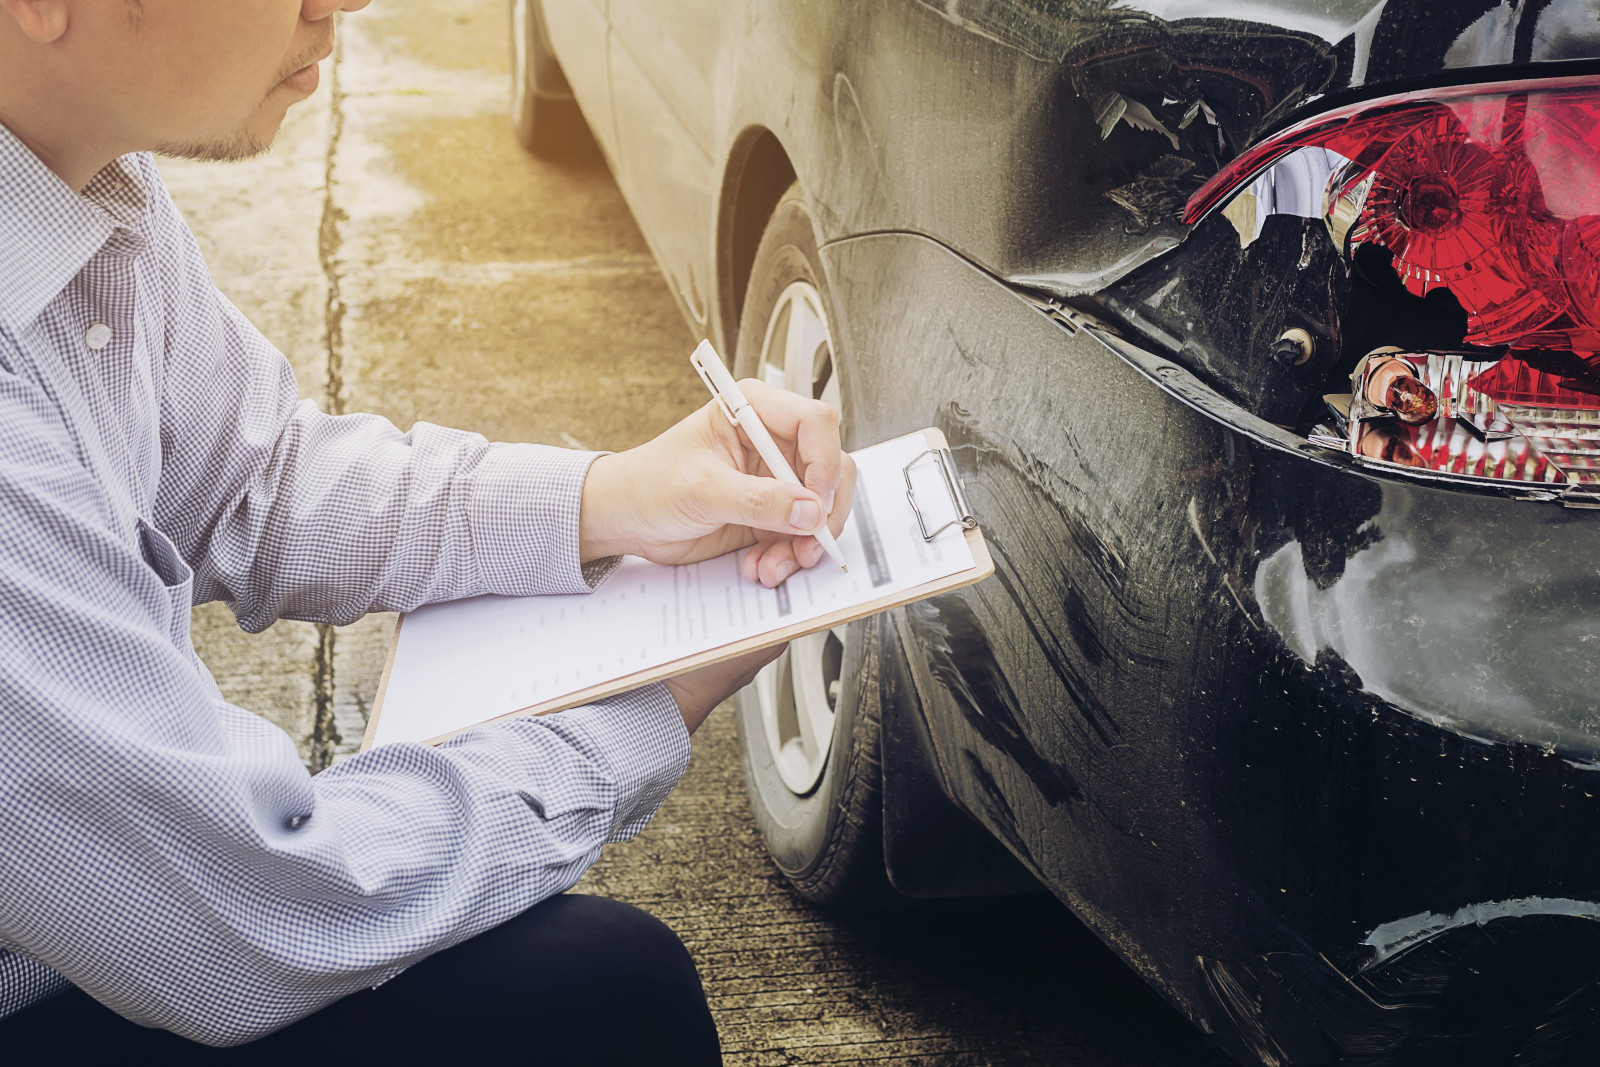

A small dent in your bumper. A scratch from a shopping cart. A crease from backing into a pole you did not see.
These situations are frustrating, but they are also common. When minor vehicle damage happens, one question usually comes up pretty quickly:
Should I file an insurance claim or just pay for the repair myself?
There is no single answer that works for every situation. The right choice can depend on the cost of the repair, your deductible, whether another driver was involved, the possibility of hidden damage, and how a claim could affect your insurance in the future.
Before you make a decision, it helps to understand what the repair may actually involve.
What Counts as Minor Vehicle Damage?
Minor damage usually refers to cosmetic or light collision damage that does not obviously affect the vehicle’s drivability.
Common examples include:
- Paint scratches
- Small dents
- Cracked or scuffed bumpers
- Side mirror damage
- Broken headlights or taillights
- Minor fender damage
- Parking lot damage
- Low-speed collision damage
The problem is that damage that looks minor from the outside is not always minor underneath.
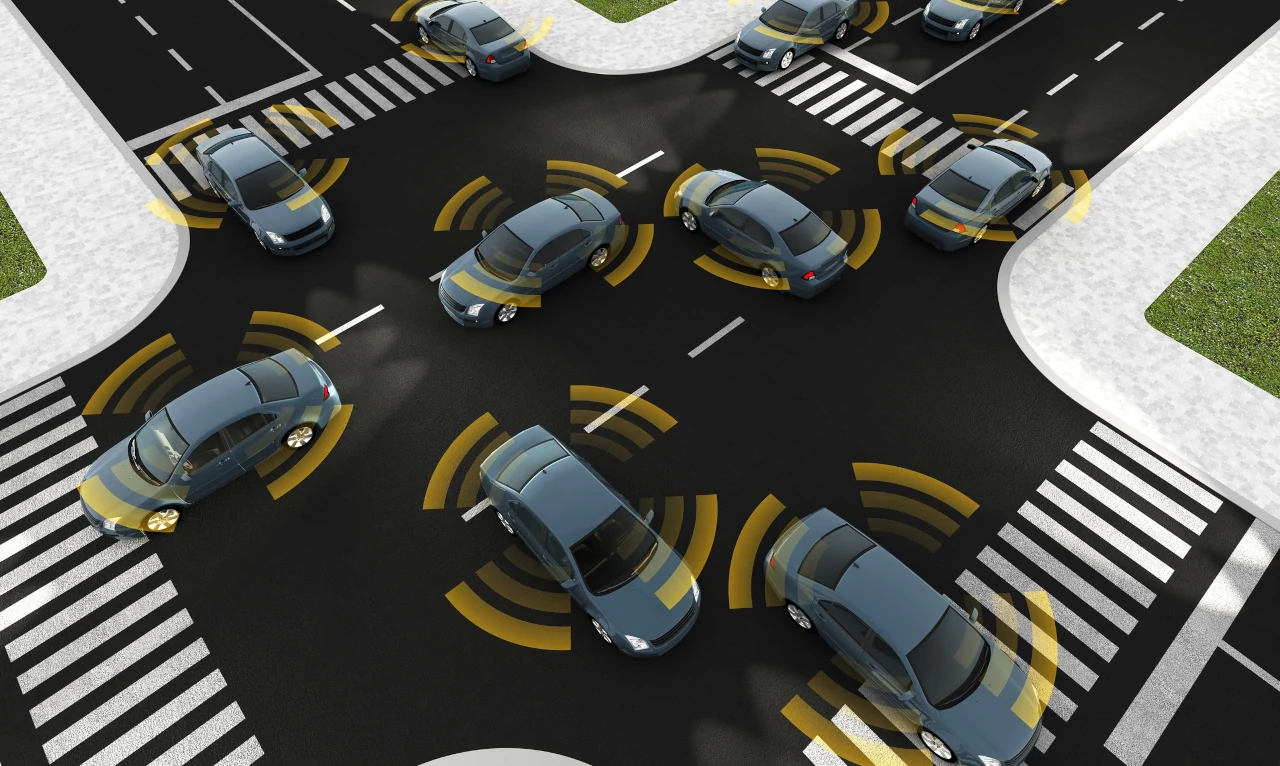
Modern bumpers, body panels, lights, cameras and sensors can make even a relatively small impact more complicated than it first appears. A damaged bumper cover, for example, may hide broken brackets or damage near sensors and wiring.
If the damage came from an accident or impact, it is worth having the vehicle inspected before assuming the problem is only cosmetic. AutoBody by Fisher provides collision repair in Anna, TX and can help identify visible and hidden damage before you decide how to handle the repair.
When Filing an Insurance Claim May Make Sense
There are situations where using insurance may be the practical choice, even when the damage initially looks minor.
1. The Repair Cost Is Well Above Your Deductible
If the repair estimate is significantly higher than your deductible, filing a claim may reduce how much you have to pay out of pocket.
For example, if your deductible is $500 and the repair estimate is $1,800, the potential insurance benefit is much greater than if the repair were only $600.
Before filing, make sure you understand what your policy covers and what portion of the repair you may still be responsible for.
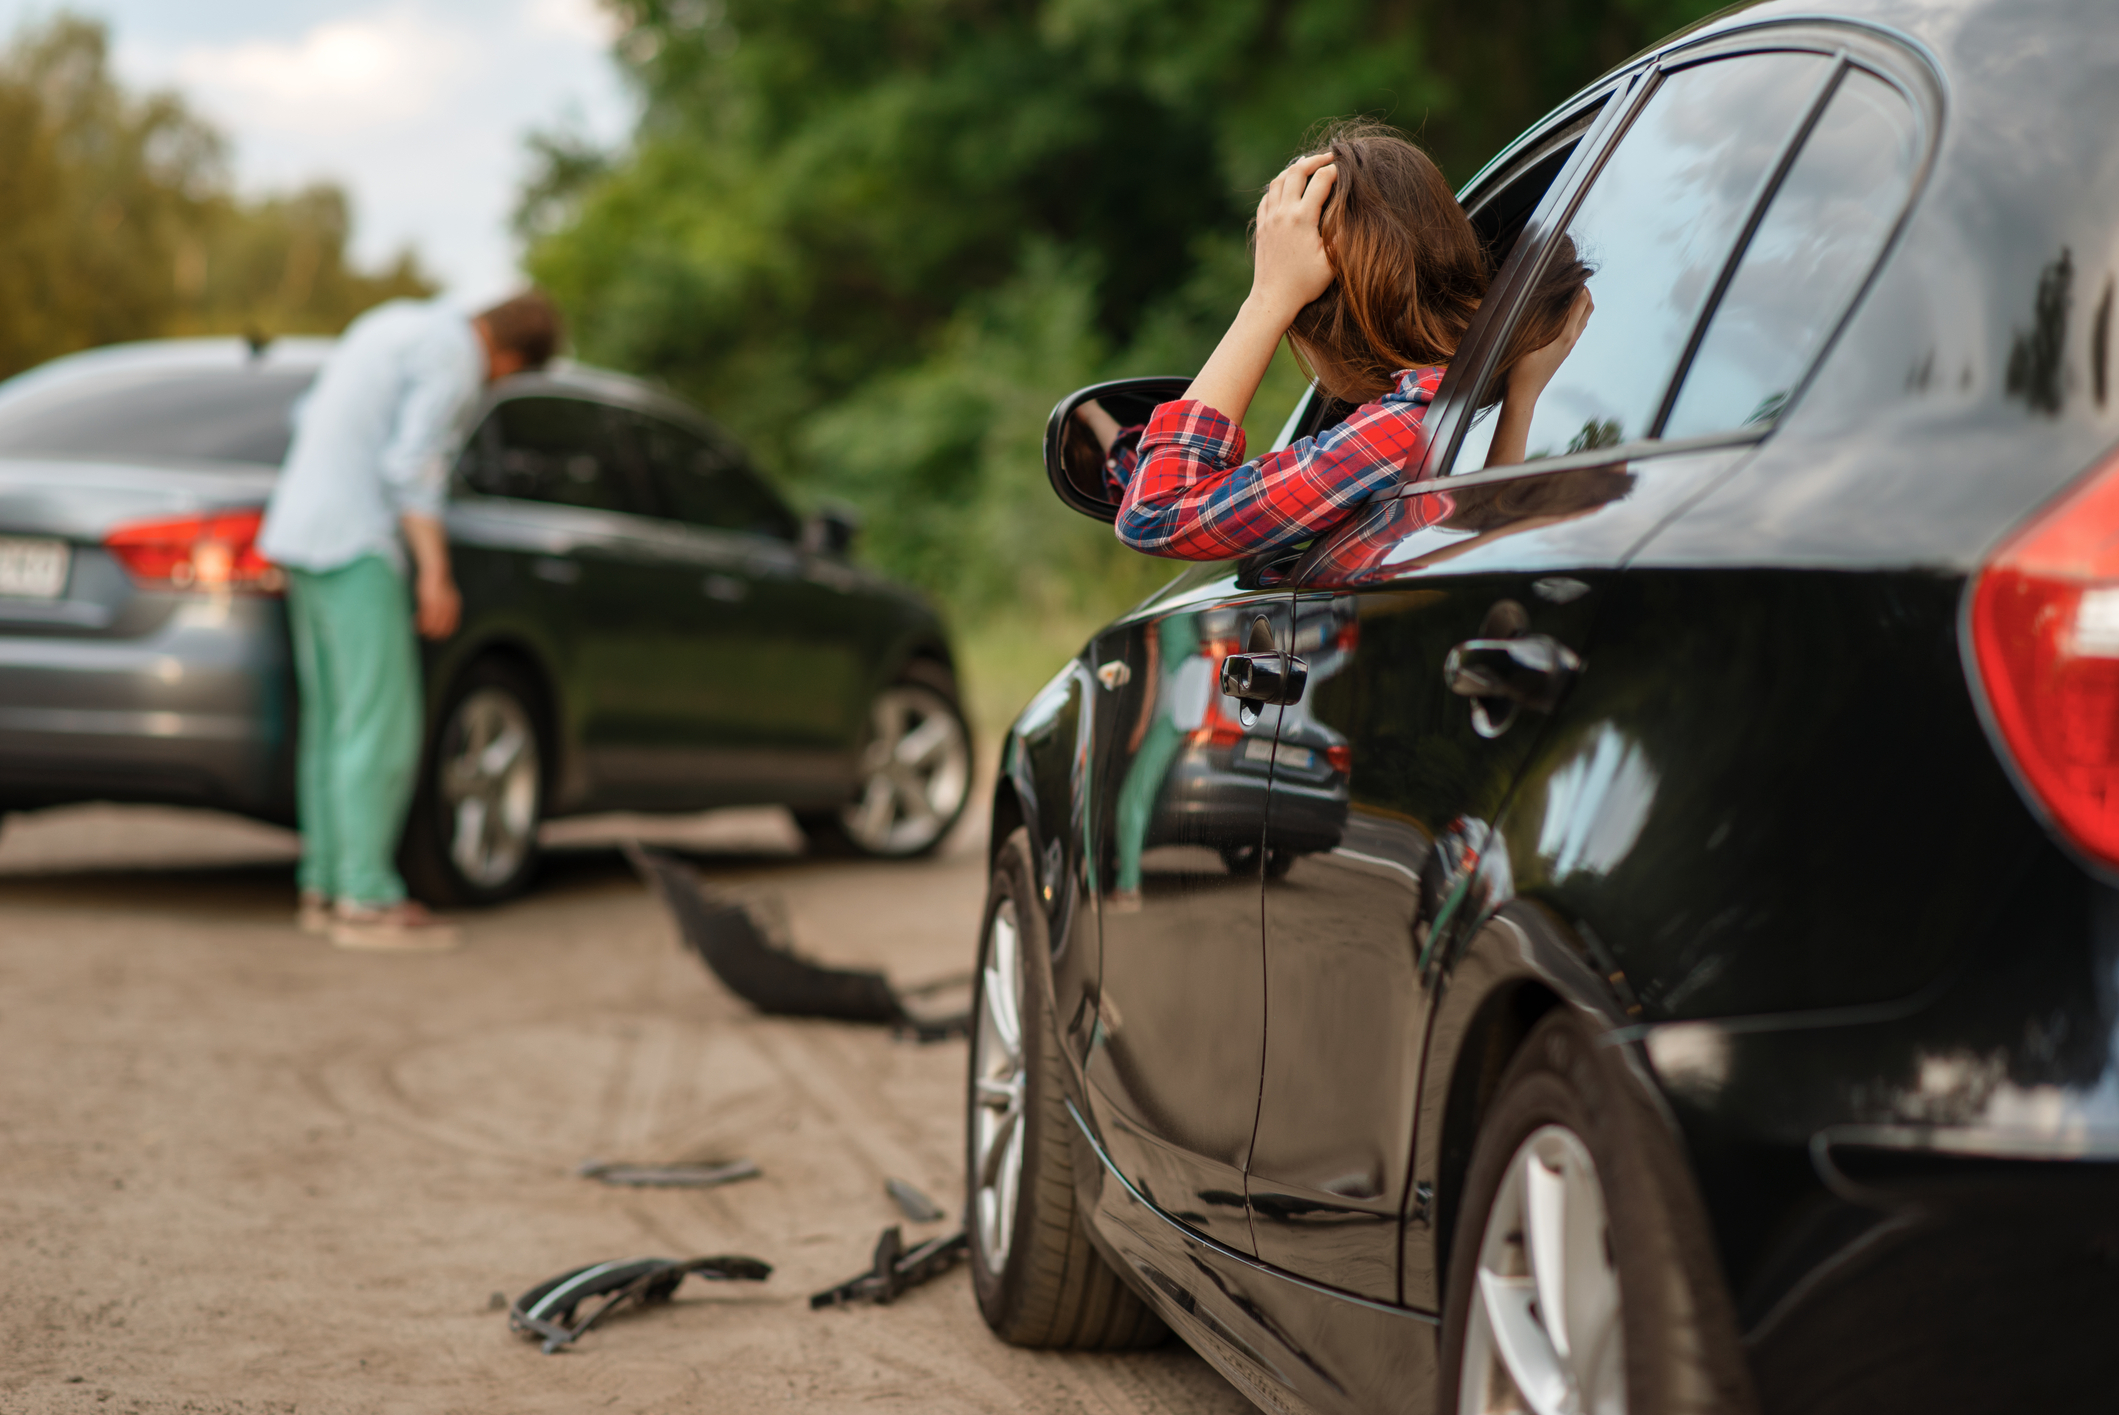
2. Another Driver Was Involved
If another driver caused the damage, their insurance may be responsible for the repair.
Document the accident carefully, exchange insurance information, take photos and confirm the claim process before repairs begin.
Even when the damage looks minor, having proper documentation can help if additional damage is discovered later.
3. The Damage Could Be Worse Than It Looks
A small impact can sometimes damage more than the visible exterior panel.
Possible hidden issues can include:
- Broken bumper brackets
- Damaged reinforcement components
- Misaligned panels
- Damage near lights or wiring
- Sensor-related problems
- Structural concerns
This is especially important on vehicles equipped with modern driver-assistance systems.
If you want to learn more, see our guide on hidden damage after an accident and our article on how minor collisions can affect vehicle sensors.
When Paying Out of Pocket May Be Worth Considering
Using insurance is not automatically the best choice for every minor repair.
There are several reasons you may want to compare the repair cost with your deductible before opening a claim.
1. The Repair Cost Is Close to Your Deductible
If your deductible is $1,000 and the repair costs $1,200, insurance may only cover a relatively small portion of the repair.
In that situation, paying out of pocket may be worth considering.
The first step is getting an accurate repair estimate so you know what you are comparing.
2. A Claim Could Affect Future Premiums
Insurance rates can change after a claim depending on factors such as your insurer, driving history, fault, location and policy.
Before filing a small claim, it may be helpful to ask your insurance agent how the claim could affect your specific policy.
Some policies also include accident forgiveness or other features that may change the decision.
3. You May Lose Claim-Free Discounts
Some insurers offer discounts to drivers who have gone a certain amount of time without filing a claim.
A small claim could potentially affect those discounts.
This varies by insurer and policy, so it is worth checking before making a decision.
4. You Have More Flexibility Paying Directly
When you pay for the repair yourself, you can often make decisions without waiting for insurance approval.
That can make sense when the repair is relatively inexpensive and you simply want to get the vehicle fixed.
Real-World Examples
Here are a few common situations that show why the answer is not always obvious.
Scenario 1: The Shopping Cart Dent
You return to your vehicle after shopping and find a dent in the door. No note, no witnesses.
The repair estimate is $450 and your deductible is $500.
What to consider: Since the repair is below the deductible, insurance may not provide any financial benefit. Paying out of pocket may make more sense.
Scenario 2: A Minor Rear-End Collision
You are rear-ended at a stoplight. The bumper does not look badly damaged, but a warning light appears and a parking sensor is no longer working.
The other driver accepts responsibility.
What to consider: Document the accident and review the claim options with the other driver’s insurer. The sensor issue may indicate damage beyond what is visible from the outside.
Scenario 3: You Back Into a Pole
You accidentally scrape and dent the rear bumper while backing up.
The repair estimate is $1,200 and your deductible is $1,000.
What to consider: The difference between paying the repair yourself and filing a claim is relatively small. You may want to compare that savings with any potential effect the claim could have on your policy.
Quick Insurance Claim Decision Guide
These general considerations can help you decide what questions to ask before filing a claim.
Paying Directly May Make Sense
Repair Is Below Your Deductible
Paying out of pocket may make more sense if insurance would provide little or no financial benefit.
Compare Carefully
Repair Is Only Slightly Above Your Deductible
Compare the immediate savings with the possible effect a claim could have on your insurance.
Review Claim Options
Repair Is Much More Than Your Deductible
Filing a claim may provide more financial benefit when the repair cost is substantially higher than your deductible.
Review Claim Options
Another Driver Caused the Damage
Document the accident and review the other driver’s insurance claim process before repairs begin.
Get the Damage Inspected
Sensors, Lights or Bumper Components Are Affected
Have the vehicle inspected before assuming the damage is only cosmetic.
Get an Estimate First
You Are Unsure What the Repair Will Cost
Get a repair estimate before deciding whether opening an insurance claim makes sense.
Check Your Policy Impact
You Have Filed Recent Claims
Ask your insurer or agent how another claim could affect your policy, discounts or future premiums.
Tips Before You Decide
Get a Repair Estimate First
You cannot make a good comparison until you know what the repair is likely to cost.
An estimate gives you a starting point for comparing the repair amount with your deductible.
Review Your Deductible
If the repair is below or only slightly above your deductible, using insurance may provide little benefit.
Consider Your Claim History
If you have filed other claims recently, you may want to ask your agent how another claim could affect your policy.
Do Not Ignore Hidden Damage
A bumper scrape or dent may look cosmetic but could involve damage underneath the surface.
If the vehicle was involved in an impact, a professional inspection can help determine whether additional repairs are needed.
Ask Your Insurance Agent Questions
Your agent can explain how your deductible, accident forgiveness, claim history and policy terms apply to your situation.
Minor Collision Damage in Anna, TX
If you are dealing with bumper damage, dents, paint damage or other minor collision damage in Anna or the surrounding North Texas area, AutoBody by Fisher can help you understand what the repair may involve before you decide how to handle the cost.
Our shop is located at:
AutoBody by Fisher
12405 Lazy Lane
Anna, TX 75409
We help drivers with:
- Collision repair
- Auto body repair
- Bumper and panel damage
- Dent repair
- Paint and refinishing
- Hidden collision damage
- Hail damage repair
- Custom body and paint work
If the damage came from an accident, visit our collision repair in Anna, TX page for more information about the repair process.
Think Beyond the Repair Cost
The decision to file an insurance claim should not be based only on the repair bill.
It can also depend on:
- Your deductible
- Who caused the damage
- Your claim history
- Your insurance policy
- The possibility of hidden damage
- How much of the repair insurance would actually cover
For minor damage, getting an estimate first often gives you the information you need to make a more informed decision.
Not Sure Whether the Damage Is Worth an Insurance Claim?
Start by finding out what the repair may involve. AutoBody by Fisher can review your vehicle damage and help you understand the repair options before you decide how to proceed.
Start an Online Estimate
Call (903) 482-5171
For more information about accident repairs, visit our
Collision Repair in Anna, TX page.